
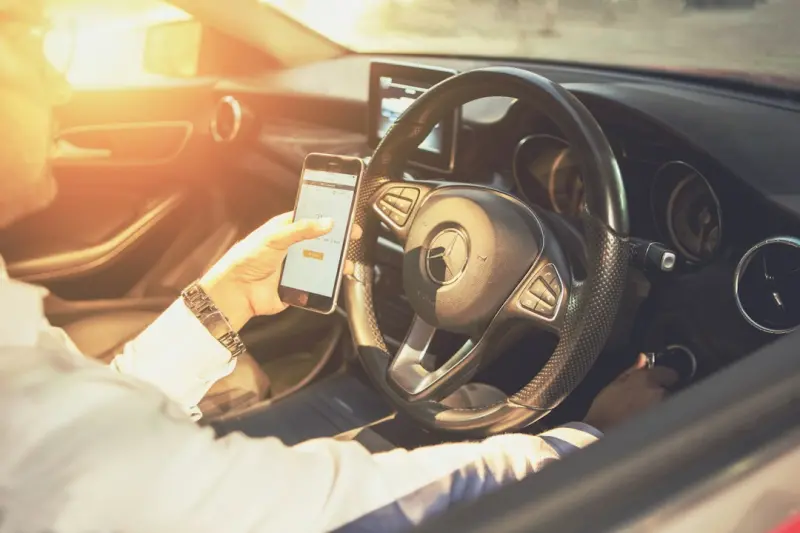
Driving the Future: How Usage‑Based Insurance Is Rewriting the Rules of Risk
When I first stepped into a conference room full of actuaries, underwriters, and tech founders, the buzzword on everyone’s lips was usage‑based insurance (UBI). It felt like watching the insurance industry finally shed its “one‑size‑fits‑all” skin and try on a sleek, data‑driven suit. As someone who has spent the better part of two decades navigating the tangled corridors of insurance law, I can tell you that the shift from traditional premiums to mileage‑or‑behavior‑based pricing isn’t just a clever marketing gimmick—it’s a seismic legal transformation.
From Static Policies to Real‑Time Risk
Traditional auto policies have long relied on static factors: age, gender, zip code, credit score, and a handful of historical claims. Those variables are static, and they’re often blunt instruments for measuring actual risk. UBI flips the script by feeding telematics, smartphone sensors, and even vehicle‑to‑infrastructure data straight into the underwriting engine.
The result? Premiums that can rise or fall month‑by‑month, reflecting how you actually drive, not how the industry thinks you’ll drive. For policyholders, this promises lower costs for safe drivers and a clear incentive to improve habits. For insurers, it promises a more granular risk pool and, theoretically, fewer catastrophic losses.
The Legal Landscape is Getting a Data Overhaul
But every technological leap brings a fresh set of legal questions. Below are the three pillars that are reshaping insurance law in the UBI era:
- Data Privacy and Consent – When insurers collect location data, acceleration forces, and even in‑car audio snippets, they’re walking a tightrope between risk assessment and privacy intrusion. The Wearable Health Tech: The Emerging Legal Landscape piece highlighted how health data regulators have started to treat granular biometric information as “sensitive.” The same logic now applies to driving data, especially when it can be cross‑referenced with other personal datasets.
- Bad‑Faith Claims Handling – Traditional insurance contracts already contain bad‑faith provisions, but the real‑time nature of UBI adds a new dimension. If an insurer decides to recalibrate a premium overnight based on a single hard‑brake event, does that constitute a breach of the implied covenant of good faith? Courts are still grappling with the answer.
- Regulatory Consistency Across Jurisdictions – In the United States, each state has its own insurance code, and many have yet to codify rules for telematics. The patchwork can create “regulatory arbitrage,” where insurers offer wildly different UBI products depending on the state’s tolerance for data collection.
Consent Is Not a One‑Time Checkbox
One of the most common missteps I see insurers make is treating the consent form as a simple “I agree” box at policy inception. In practice, consent must be ongoing, transparent, and revocable. This mirrors the principles laid out in the European General Data Protection Regulation (GDPR) and the California Consumer Privacy Act (CCPA). For example, a policyholder should be able to:
- See exactly which data points are being collected (speed, location, time of day, etc.).
- Understand how each data point influences premium adjustments.
- Opt out of specific data streams without nullifying the entire policy.
When insurers fail to provide this level of granularity, they risk not only regulatory fines but also class‑action lawsuits alleging deceptive practices. The line between a “usage‑based” model and a “surveillance” model can become blurry, and that’s where the courts will step in.
Bad‑Faith Premium Adjustments: A Growing Litigation Hotspot
Imagine you’re a rideshare driver who logged 1,200 safe miles in a month, only to see the premium jump after a single hard brake recorded during a rainy afternoon. The insurer might argue that the event signals higher risk, but you could counter that the overall data set still reflects a safe driver profile. This tension sets the stage for a new breed of bad‑faith disputes.
Historically, courts have evaluated bad‑faith claims by looking at whether the insurer acted “unreasonably” or “without proper cause.” In the UBI context, “reasonableness” will increasingly be measured against the insurer’s own algorithms. If an underwriter’s model is proprietary, does that protect them from scrutiny? More likely, regulators will demand algorithmic transparency, especially when premium adjustments are frequent and material.
Regulatory Patchwork: State by State
Let’s take a quick tour of the United States. California, with its robust privacy statutes, requires insurers to provide clear, concise notices about telematics data usage. New York, on the other hand, has a more permissive stance but demands that any data‑driven premium change be disclosed at least 30 days before it takes effect. Meanwhile, Texas recently introduced a bill that caps premium adjustments based on telematics at 10% per annum.
Internationally, the picture is equally fragmented. The United Kingdom’s Financial Conduct Authority (FCA) has issued guidance encouraging insurers to adopt “fair and transparent” data practices, while the European Union is moving toward a unified telematics framework under the upcoming Digital Services Act revisions. For multinational insurers, the compliance burden can feel like navigating a labyrinth of contradictory rules.
UBI and the Rise of Embedded Insurance
One exciting offshoot of usage‑based models is embedded insurance. Think of a car‑sharing platform that automatically adds a per‑hour liability policy based on the user’s driving behavior during that session. The policy isn’t a standalone contract; it lives within the platform’s ecosystem, triggered and terminated in real time.
Embedded insurance raises its own legal challenges:
- Contractual Clarity – Users must understand that they are entering into an insurance contract every time they press “start.” The fine print can’t be hidden in a Terms of Service scroll box.
- Regulatory Licensing – Who is the insurer? The platform, the underwriting carrier, or both? Licensing requirements can differ dramatically based on jurisdiction.
- Claims Processing – With a policy that can evaporate within minutes, traditional claims timelines become obsolete. Insurers need to build rapid adjudication pipelines, often leveraging AI, which again loops back to data‑privacy concerns.
Cross‑Sector Lessons: What Insurance Can Learn from Tech
Tech companies have been dealing with real‑time data consent for years. Look at how mobile app developers implement “privacy dashboards” that let users toggle data collection on the fly. Insurance carriers can borrow this model, creating driver dashboards that display:
- Current mileage and driving score.
- Projected premium impact for the next billing cycle.
- Options to opt in or out of specific data streams.
Such transparency not only builds trust but also provides a defensible record should a regulator or a court question the insurer’s methodology.
Future‑Proofing Your UBI Program
To stay ahead of the legal curve, insurers should consider the following best practices:
- Algorithm Audits – Conduct regular, independent audits of the risk‑scoring models. Document the rationale behind each data point and its weight.
- Dynamic Consent Frameworks – Build consent mechanisms that can be updated without requiring a full policy rewrite. Offer granular opt‑out options.
- State‑Specific Compliance Teams – Assign dedicated compliance officers to monitor evolving state regulations and adjust the UBI product accordingly.
- Claims Transparency – Implement real‑time claim status updates, especially for embedded policies where the coverage window is narrow.
- Cross‑Industry Partnerships – Work with telematics providers, data privacy experts, and consumer advocacy groups to co‑create standards that satisfy both risk assessment needs and consumer rights.
Case Study: A Real‑World UBI Dispute
Last quarter, a mid‑size insurer faced a class‑action lawsuit after a subset of policyholders claimed that their premiums spiked following a software update that unintentionally altered the telematics algorithm’s weighting of “night‑time driving.” The plaintiffs argued that the insurer failed to disclose the algorithmic change and that the abrupt premium hikes constituted a breach of the duty of good faith.
The court’s decision hinged on two factors:
- Disclosure – The insurer had sent an email about the update, but it was buried in a generic “product news” newsletter. The judge ruled this was insufficient under the state’s unfair trade practices statutes.
- Reasonableness – Expert testimony showed that the new weighting was statistically sound, but the insurer had not provided a clear rationale to policyholders. The court found that the lack of transparency violated the implied covenant of good faith.
The settlement included a $12 million fund and a mandate for the insurer to develop a transparent, user‑friendly telematics dashboard—a cautionary tale for any carrier looking to roll out or modify UBI products.
Looking Ahead: The Convergence of UBI and Autonomous Vehicles
While autonomous vehicles (AVs) are still in the testing phase, the data ecosystems they generate will inevitably overlap with UBI platforms. As AVs become more prevalent, insurers will have to decide whether to treat telematics data as a proxy for driver behavior or as a proxy for vehicle performance. The legal distinction could determine who bears the risk—the human occupant, the software developer, or the vehicle manufacturer.
This upcoming convergence underscores a broader point: usage‑based insurance is not a static innovation; it’s a moving target that will continually intersect with emerging tech, regulatory shifts, and consumer expectations.
Final Thoughts: Embrace the Data, Respect the Rights
Usage‑based insurance offers a tantalizing promise: a more equitable premium structure that rewards safe behavior and penalizes risk in real time. However, that promise can only be fulfilled if insurers walk the tightrope of data utilization with a steadfast commitment to transparency, fairness, and legal compliance.
As the industry continues to innovate, the legal community will play a pivotal role in shaping the rules of the road. By building robust consent frameworks, maintaining algorithmic accountability, and staying ahead of the patchwork regulatory landscape, insurers can turn the UBI revolution from a legal minefield into a competitive advantage.
For those curious about how other data‑driven insurance models are navigating the law, the Parametric Insurance: The New Frontier of Weather‑Triggered Coverage article offers a compelling parallel on how transparency and clear triggers can mitigate disputes.
In the end, the success of usage‑based insurance will hinge on one simple truth: data is powerful, but it must be wielded responsibly. The law, as ever, is there to ensure that power doesn’t become a tool for exploitation. Let’s make sure it stays that way.
Allison Jarvis is a dynamic digital media and marketing professional dedicated to driving brand growth through impactful storytelling. With a sharp eye for market trends and a passion for data-driven strategies, she specializes in building cohesive online identities that resonate with modern audiences. Allison blends creative content production with robust analytics to maximize engagement and deliver measurable ROI. She continuously explores emerging digital tools to keep her projects ahead of the curve.
Related Posts
Embedded Insurance in SaaS: Navigating the Legal Minefield
Embedded insurance is reshaping SaaS business models, but it brings complex legal challenges. This a... Read More
Why SaaS Leaders Must Rethink Their Cyber Insurance Policies
Cyber‑insurance isn’t a set‑and‑forget solution for SaaS companies. This post uncovers hidde... Read More
Navigating the New Frontier of Cyber Insurance Laws
A deep dive into emerging cyber insurance laws, practical compliance steps, and the role of AI in un... Read More
Top Posts
Virtual Courtrooms Are Redefining Family Law: What Parents Need to Know
Virtual courtrooms are reshaping family law, offering convenience but also new challenges. This post examines procedural shifts, equity concerns, digital parent...Read More
Rebuilding Financial Independence After Divorce
Learn how to rebuild credit, protect assets, and create new income streams after divorce. This guide offers actionable steps for financial independence and pers...Read More
The Power of Semantic Topic Clusters: A Data‑First Blueprint for SEO Success
Learn a data‑first approach to SEO by creating semantic topic clusters that combine pillar pages, structured data, and continuous testing, driving authority a...Read More
When the Office Watches: Unpacking the Legal Maze of Employee Surveillance
A comprehensive guide to the legal challenges of employee surveillance, offering practical compliance steps, real‑world case studies, and future‑proof strat...Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!