
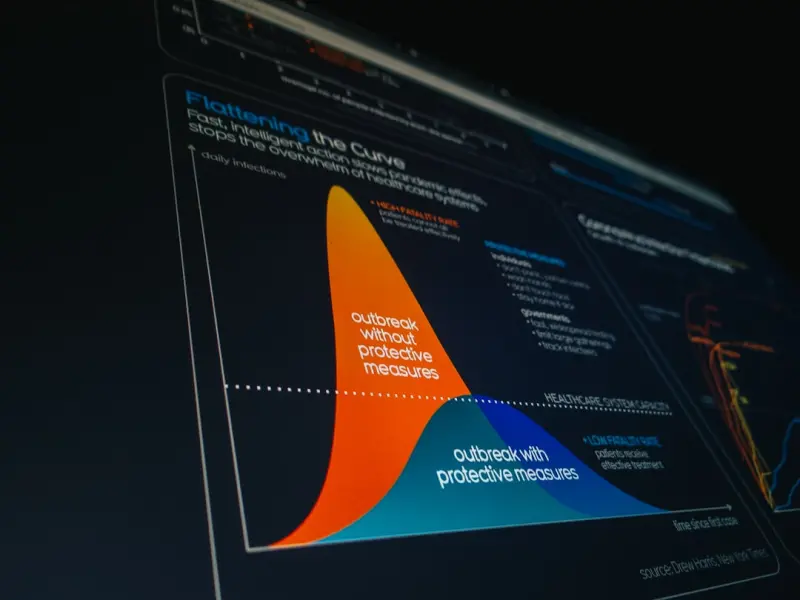
Parametric Insurance: A Legal Frontier Worth Watching
When I first stumbled into the world of insurance law, the conversation was all about indemnity, bad faith, and the ever‑present dance between underwriters and claimants. Fast forward a few years, and the buzz in boardrooms has shifted to something that feels almost futuristic: parametric insurance. If you’ve ever wondered why a farmer in the Midwest can receive a payout days after a drought is declared, or how a coastal city can instantly tap a cash reserve after a hurricane, you’re about to get the inside track on the legal scaffolding that makes it all possible.
What Exactly Is Parametric Insurance?
Traditional indemnity policies hinge on the actual loss a policyholder suffers. A damaged roof means an assessor walks the site, quantifies the cost to repair, and then the insurer pays. Parametric policies, by contrast, sidestep the loss‑assessment step entirely. They trigger a payout when a pre‑defined, objectively measurable event occurs – think wind speed exceeding 150 mph, rainfall surpassing 10 inches in 24 hours, or a seismic reading hitting a certain magnitude.
This “trigger‑first, loss‑second” model promises speed, transparency, and lower administrative overhead. But it also raises novel legal questions that courts and regulators are only beginning to grapple with.
The Appeal for Businesses and Governments
From a risk‑management perspective, speed is king. In the aftermath of a natural disaster, cash flow can be the difference between survival and bankruptcy. Parametric contracts can deliver funds within hours, not weeks. Governments love the predictability too: they can budget for catastrophe relief based on known trigger thresholds, reducing the need for ad‑hoc appropriations.
For insurers, the model offers a cleaner risk profile. Because payouts are tied to clear, quantifiable metrics, the exposure is easier to model and re‑insurance can be more straightforward. However, this simplification does not eliminate legal complexity – it merely reshapes where the friction points appear.
Key Legal Issues Emerging from the Parametric Model
- Definition of the Trigger: The language used to define the trigger must be precise. Ambiguities can lead to disputes over whether the event truly met the contractual threshold. Courts have started to interpret “reasonable certainty” as the standard, but the line between a technical measurement error and a bona fide trigger can be blurry.
- Basis Risk: This is the risk that the payout does not fully cover the actual loss because the chosen index doesn’t perfectly correlate with the loss experienced. While technically an actuarial issue, basis risk often surfaces in litigation when policyholders claim the payout is “inadequate.” The legal debate revolves around whether the insurer breached its duty by selecting an unsuitable index.
- Regulatory Oversight: In many jurisdictions, parametric products fall under the same regulatory umbrella as traditional policies, but regulators are still catching up on disclosure requirements, capital adequacy, and consumer protection safeguards. Some regulators are considering a separate “index‑linked” category to address the unique nature of these contracts.
- Data Integrity and Sources: Since triggers rely on external data – weather stations, satellite imagery, seismic sensors – the provenance and reliability of that data become legal touchstones. If a sensor malfunctions or a data provider supplies inaccurate readings, who is liable? This issue dovetails with broader data‑trust concerns, as highlighted in the discussion about data trusts and fiduciary duties.
- Cross‑Border Enforcement: Parametric contracts are increasingly global, especially for multinational supply chains. Enforcing a trigger that originated in one legal regime while the claim is made in another raises conflict‑of‑law questions that courts have yet to fully resolve.
Recent Case Law: Setting the Stage
While the body of case law is still thin, a handful of decisions are already shaping the terrain. In Coastal Re Ltd. v. State Insurance Commission, the court upheld a payout despite the insurer’s argument that the wind speed measurement was “slightly” below the contractual threshold. The judge emphasized the principle of “objective trigger compliance” and warned against “microscopic scrutiny” that defeats the purpose of a parametric design.
Conversely, the Midwest Agribusiness v. FarmSure case turned on the issue of basis risk. The plaintiff argued that the rainfall index failed to capture localized flooding that devastated their fields. The court ruled that the insurer had a duty to ensure the index was “reasonably correlated” with the insured loss, opening the door for future litigation over index selection.
These rulings illustrate a growing judicial willingness to engage with the technical underpinnings of parametric contracts, rather than treating them as a black box.
Contract Drafting Tips: Mitigating Future Disputes
Given the nascent state of jurisprudence, the safest approach is to anticipate potential friction points at the drafting stage. Below are practical clauses and strategies that I’ve seen work well:
- Clear Metric Definitions: Spell out the data source (e.g., “National Weather Service”), measurement methodology, and any rounding rules.
- Grace Periods and Tolerances: Include a modest buffer (e.g., “±2 mph”) to account for sensor variance, thereby reducing the chance of a technical miss.
- Basis Risk Disclosure: Require the insured to acknowledge that the index may not perfectly match actual loss, and provide a “gap‑coverage” option if they desire full indemnity.
- Data Verification Process: Outline a dispute‑resolution mechanism where both parties can request an independent audit of the trigger data.
- Force‑Majeure and Contingency Clauses: Explicitly address scenarios where the data source itself is disrupted (e.g., satellite outage).
- Governing Law and Jurisdiction: Choose a forum with a track record of handling complex financial contracts, and consider arbitration clauses for speed.
Regulatory Trends to Watch
Regulators across the globe are beginning to publish guidance. In the United States, the NAIC (National Association of Insurance Commissioners) has released a Model Law for Index‑Linked Insurance Products, which emphasizes transparency, consumer education, and capital requirements proportional to the volatility of the underlying index.
In the European Union, the Solvency II framework is being updated to better accommodate parametric risk. The EU’s “Insurance‑Linked Securities” (ILS) regime now recognizes parametric contracts as a distinct asset class, requiring insurers to hold specific capital buffers.
Asian markets, particularly Japan and Singapore, are experimenting with “catastrophe bonds” that are essentially parametric contracts sold to investors. These experiments are prompting local regulators to consider new disclosure norms for both insurers and capital market participants.
Technology’s Role: From Sensors to Smart Contracts
The reliability of triggers hinges on the technology that captures the data. Advances in IoT (Internet of Things) sensors, satellite remote sensing, and AI‑driven data validation are tightening the accuracy gap. Some innovators are even embedding parametric triggers directly into smart contracts on blockchain platforms. While this promises automatic, tamper‑proof payouts, it also layers additional legal considerations around code immutability, jurisdiction, and the enforceability of digital agreements.
One real‑world example is a recent partnership between a Caribbean reinsurer and a satellite data provider, where a smart contract automatically released funds once a specific sea‑surface temperature anomaly was recorded. The arrangement bypassed traditional claim adjusters entirely, but it also raised questions about who bears responsibility if the satellite misreads the temperature—a scenario that will likely end up in court sooner rather than later.
Comparative Insight: How Parametric Insurance Differs From Traditional Use‑Based Policies
It’s tempting to lump all “data‑driven” insurance products together, but there’s a subtle yet important distinction. While usage‑based insurance models hinge on the behavior of the insured (e.g., miles driven, driving speed), parametric contracts are triggered by external, third‑party events. This means the insured’s control over the trigger is limited, shifting the risk calculus in unique ways. For lawyers, this distinction translates into different liability pathways and regulatory lenses.
Strategic Takeaways for Insurers, Brokers, and Policyholders
Whether you sit on the underwriting side, advise corporate risk teams, or sit at the negotiating table as a broker, here are three strategic imperatives:
- Invest in Data Governance: Your contract’s enforceability will be as strong as the data pipeline that feeds it. Establish robust data‑validation protocols and consider partnering with reputable data providers.
- Educate Stakeholders: Many policyholders still think of insurance in the indemnity sense. Clear communication about how parametric payouts work—and what they do not cover—is essential to set expectations and avoid disputes.
- Stay Ahead of Regulation: As regulators draft specific rules, early compliance can be a market differentiator. Participate in industry working groups to shape policy and gain insight into upcoming requirements.
Looking Ahead: The Next Wave of Innovation
Parametric insurance is still in its adolescence, but the trajectory is unmistakable. As climate change intensifies the frequency of extreme events, the demand for swift, reliable payouts will only grow. Meanwhile, the convergence of AI, IoT, and blockchain will tighten the feedback loop between trigger detection and payment execution.
From a legal perspective, the most exciting (and challenging) frontier will be the intersection of technology governance and contractual enforceability. Expect more cases that dissect the minutiae of sensor calibration, more regulatory sandboxes that experiment with “code‑as‑law,” and a gradual shift in the industry’s risk‑transfer vocabulary.
In short, parametric insurance is not just a clever product innovation; it’s a catalyst reshaping the legal architecture of risk. For those willing to understand its intricacies, the opportunity to pioneer new legal frameworks—and to protect clients against the unpredictability of a changing world—is immense.
Kris Kennel is a Paralegal outside of Austin, Texas where he spends most of his time helping users with legal matters that concern them. When he is not working he enjoys time with his wife and kids.
Related Posts
Parametric Insurance: Speed, Data, and the Legal Tightrope
A deep dive into parametric insurance’s rapid payouts, data‑driven triggers, and the legal safeg... Read More
When Floods Hit: Unraveling Insurance Law in the Climate Era
As extreme weather reshapes our homes, insurance law faces new tests. I break down claim challenges,... Read More
Insurance Law in 2024: Navigating Family Risks with Confidence
A deep dive into 2024’s insurance law shifts reveals essential strategies for families facing divo... Read More
Top Posts
When Vows Meet Virtual Assets: Marriage Law in the Digital Frontier
A deep dive into the challenges and strategies for couples navigating marital property law in the age of digital assets, from crypto wallets to tokenized real e...Read More
Seeing Beyond the Wheel: Rethinking Impaired Driving in the Gig Economy
A deep dive into how telemetry, wearables, embedded insurance, and driver representation can transform impaired driving from a tragic reality into a preventable...Read More
When Algorithms Meet Crime: A Criminal Lawyer’s Perspective on the Digital Frontier
A seasoned criminal lawyer reveals how AI, surveillance, and digital evidence are redefining defense strategies, balancing public safety with individual rights....Read More
Why SaaS Leaders Must Rethink Their Cyber Insurance Policies
Cyber‑insurance isn’t a set‑and‑forget solution for SaaS companies. This post uncovers hidden exclusions, regulatory overlaps, and practical steps to en...Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!