The Home Office Economy: Unpacking the Labour Law Ripple Effect of Remote‑Work Stipends
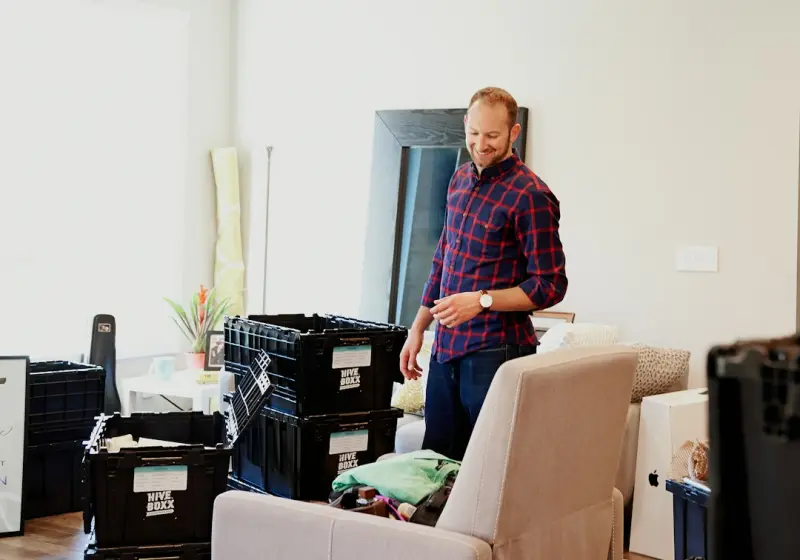
When the pandemic forced desks onto kitchen tables, many employers responded with a simple, well‑intentioned question: “Can we help cover your home‑office costs?” The answer arrived in the form of stipends, reimbursements, and “flex‑budget” programs. On the surface, these gestures appear generous—an extra $50 for internet, a one‑off $200 for an ergonomic chair. Yet, underneath the goodwill lies a rapidly evolving legal landscape that few HR leaders have fully mapped.
In my years consulting for midsize tech firms, I’ve watched the home‑office economy transform from a temporary fix into a permanent fixture of employment contracts. This shift raises three core labour‑law questions that demand immediate attention:
- What qualifies as a reimbursable expense versus a taxable benefit?
- How do remote‑work stipends intersect with minimum‑wage and overtime calculations?
- What obligations do employers have when they mandate equipment upgrades or software subscriptions?
Answering these questions isn’t just about compliance; it’s about protecting the employer‑employee relationship from hidden disputes that can quickly spiral into costly litigation.
1. Stipends vs. Reimbursements: The Legal Thin Line
Labour statutes across most jurisdictions distinguish between a reimbursement—a repayment for an employee‑incurred expense—and a stipend—a fixed allowance meant to cover anticipated costs. The distinction matters because reimbursements are typically non‑taxable, whereas stipends can be treated as taxable income unless they meet specific criteria.
In practice, the line blurs when a company offers a “home‑office allowance” without demanding receipts. Courts have started to view such blanket allowances as deemed wages. For example, a recent appellate decision in the Midwest held that a $100 monthly stipend, paid without any documentation requirement, constituted taxable income and therefore required payroll tax withholding.
To mitigate risk, employers should adopt a clear policy that:
- Defines which expenses are eligible (e.g., broadband, office furniture, peripheral devices).
- Specifies the documentation required (receipts, vendor invoices, or a simple expense form).
- Outlines the timing of reimbursement (within 30 days of submission) or the frequency of stipend payments (monthly, quarterly).
By structuring the program as a true reimbursement—requiring proof of purchase and limiting the amount to the actual cost—companies can keep the benefit non‑taxable and stay on the safe side of labour‑law compliance.
2. Minimum‑Wage, Overtime, and the Hidden Hours Trap
One of the most under‑examined consequences of remote‑work allowances is their impact on minimum‑wage calculations. If an employer mandates that an employee purchase a standing desk and then provides a stipend that does not fully cover the cost, the employee effectively absorbs a portion of the expense out of pocket. Some jurisdictions treat that out‑of‑pocket cost as a deduction from wages, potentially driving the employee’s effective hourly rate below the statutory minimum.
Similarly, overtime rules can be triggered unintentionally. Suppose a salaried employee receives a monthly $250 “productivity bonus” tied to the use of a company‑provided software suite. If the bonus is tied to hours worked beyond the standard 40‑hour week, it may be re‑characterized as overtime pay, especially when the employee’s job classification is non‑exempt.
To stay compliant, businesses should:
- Conduct a minimum‑wage audit that incorporates any recurring stipends or mandatory purchases.
- Clearly label any performance‑based bonuses as discretionary and ensure they are not contingent on overtime hours.
- Consult local wage‑and‑hour regulations before instituting mandatory equipment purchases, as some states consider such requirements a wage deduction.
3. Mandatory Tools, Software Licenses, and the “Work‑From‑Home” Contract Clause
Beyond physical equipment, many employers are now requiring employees to subscribe to premium software—project‑management platforms, VPN services, or cloud‑storage solutions—under the banner of “security compliance.” When the cost is billed directly to the employee, the employer may be shifting a legal responsibility that traditionally belongs to them.
From a labour‑law standpoint, mandating paid tools can be interpreted as an unlawful deduction from wages if the employee is not compensated for the expense. Moreover, if the software is essential for job performance, the employer may be liable for any resulting work‑related injuries caused by software glitches or security breaches.
Best practice dictates that employers:
- Provide the necessary tools at no cost to the employee, or
- Offer a reimbursement program that mirrors the reimbursement model discussed earlier, with clear documentation requirements.
When drafting remote‑work contracts, include a clause that explicitly outlines equipment and software responsibilities, and reference the company’s policy on employee surveillance to demonstrate a holistic approach to compliance.
4. The Intersection of Remote‑Work Stipends and Collective Bargaining
Unionized workplaces are beginning to grapple with the same issues. In sectors where collective bargaining agreements (CBAs) dictate wage structures and benefits, any unilateral implementation of home‑office stipends may violate the agreement’s terms.
Recent negotiations in the manufacturing sector revealed a clause that explicitly prohibits “unilateral deductions or additions to wages without union consent.” Employers attempting to introduce a “remote‑work equipment fund” without consulting the union risk triggering grievance procedures and potentially illegal bargaining practices.
The safe route is to:
- Engage union representatives early in the policy‑design process.
- Draft a clear amendment to the CBA that outlines stipend eligibility, amounts, and repayment procedures.
- Provide transparent reporting on how stipends affect collective wage calculations.
5. International Perspectives: When a Global Workforce Meets Local Labour Laws
Multinational companies often assume that a uniform stipend policy can be rolled out across borders. In reality, each jurisdiction brings its own set of rules. For instance, the European Union’s Remote Work Directive (adopted in recent years) mandates that employers conduct a “risk assessment” of home‑office setups and provide “reasonable equipment.” Failure to do so can result in fines and mandatory remediation.
In contrast, several Asian economies treat any employer‑provided allowance as taxable income regardless of documentation, compelling firms to withhold payroll taxes on the stipend amount.
To navigate this complexity:
- Map out the legal requirements of each country where remote employees reside.
- Implement localized stipend structures that comply with national tax codes and wage‑minimum rules.
- Leverage a global HR platform that can automatically adjust stipend payments based on local regulations.
6. Future‑Proofing: Building a Resilient Remote‑Work Compensation Framework
As remote work becomes a permanent fixture rather than an emergency measure, the need for a robust, future‑proof compensation framework grows. Companies that treat home‑office stipends as an afterthought risk falling into a compliance quagmire. Here’s a roadmap to stay ahead:
Step 1 – Conduct a Comprehensive Cost‑Benefit Analysis
Quantify the average cost of essential home‑office equipment and compare it against the stipend amount. Use the data to determine whether a reimbursement model or a fixed stipend better aligns with budgetary goals and legal compliance.
Step 2 – Draft a Stand‑Alone Remote‑Work Policy
Separate this policy from the general employee handbook. Include sections on:
- Eligibility (full‑time vs. part‑time, tenure requirements).
- Approved expenses and caps.
- Documentation and audit procedures.
- Tax implications and payroll handling.
- Review cadence (e.g., annual reassessment).
Step 3 – Integrate with Existing Compliance Playbooks
Cross‑reference the remote‑work policy with existing compliance initiatives such as biometric privacy frameworks and data‑security protocols. This ensures a cohesive approach to employee privacy, data handling, and equipment safety.
Step 4 – Train Managers and HR Professionals
Equip line managers with the knowledge to approve expenses correctly and flag potential wage‑deduction issues. Regular training sessions reduce the risk of inadvertent non‑compliance.
Step 5 – Monitor, Audit, and Iterate
Set up quarterly audits to verify that stipends are being processed correctly, that tax withholdings are accurate, and that employees are not inadvertently falling below minimum‑wage thresholds.
Conclusion: Turning Stipends From a Legal Minefield Into a Competitive Advantage
When executed with precision, remote‑work stipends can be a powerful recruitment and retention tool, signaling that an employer values flexibility and employee well‑being. However, without a clear legal framework, those same stipends can become a liability, exposing organizations to wage‑law violations, tax penalties, and union disputes.
By treating home‑office compensation as an integral component of labour‑law strategy—complete with documentation requirements, wage‑impact analysis, and cross‑jurisdictional awareness—companies not only safeguard themselves against litigation but also build a reputation as a forward‑thinking, compliant employer.
In the evolving world of remote work, the true competitive edge lies not in the size of the stipend, but in the robustness of the compliance architecture that supports it.
Liam James Professor with a PHD. & content creator with a passion for sparking curiosity and sharing knowledge. Driven by the joy of learning and storytelling, I bring ideas to life in every project. Always exploring, always teaching.
Related Posts
Algorithmic Scheduling and the New Labour Law Frontline
A deep dive into the legal fallout of algorithmic scheduling, the hidden overtime traps, and practic... Read More
Reimagining Collective Bargaining for the Gig Economy
A fresh look at how labour law can evolve to give platform workers real collective power, from hybri... Read More
Rethinking Worker Classification: The Legal Frontier of Platform Labor
An in‑depth look at the challenges of classifying gig workers, the rise of portable benefits, and ... Read More
Top Posts
Financial Forensics: A New Edge in Child Custody Battles
Financial forensics is reshaping child custody battles, revealing hidden crypto wallets, intellectual property income, and other obscure assets. Learn how trans...Read More
Guarding Digital Gold: Trust Strategies for Crypto and NFTs
Modern estate planning must evolve to safeguard digital wealth. This guide explains how to integrate cryptocurrency and NFTs into trusts, covering asset identif...Read More
Why AI-Generated Inventions Are Redefining Patent Law
Generative AI is reshaping patent law, forcing a rethink of inventorship, disclosure, and protection. This post breaks down the legal dilemmas, offers a strateg...Read More
Gig Economy Worker Classification: What Employers and Contractors Must Know
A practical guide to gig‑economy worker classification, highlighting legal risks, best‑practice strategies, and emerging trends for employers and independen...Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!