
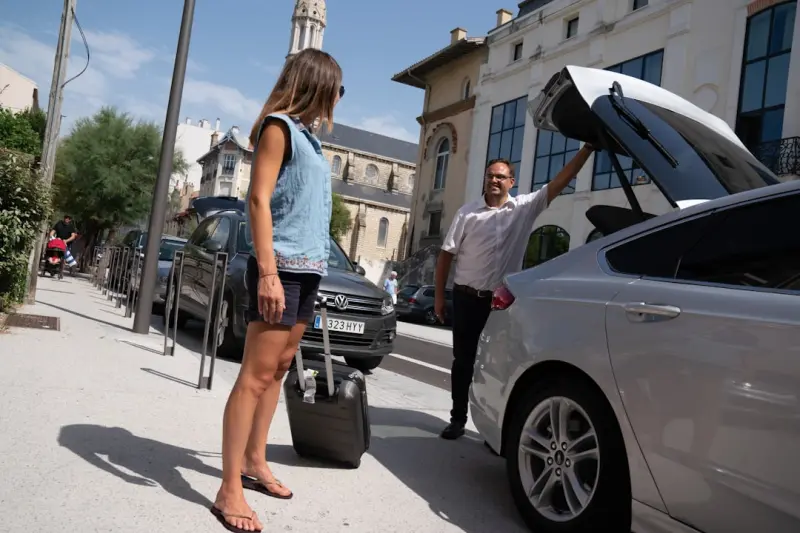
Why Peer‑to‑Peer Car Sharing Is More Than Just a Convenience
When I first saw a neighbor list their sedan on a sharing platform, I thought it was a clever way to offset depreciation. Fast‑forward a few years, and the concept has exploded into a multi‑billion‑dollar ecosystem that rivals traditional rental agencies. But convenience comes with a legal price tag that many owners, renters, and platform operators overlook until a claim lands on their doorstep.
The Ownership‑vs‑User Dichotomy
At the heart of every dispute is the question: who really owns the risk? In a traditional lease, the lessor retains title and the lessee assumes limited use. In a peer‑to‑peer (P2P) arrangement, the vehicle remains the owner’s property, yet the platform positions the renter as a “temporary driver.” This creates a gray area where statutes, contracts, and insurance policies intersect.
Most states still apply the traditional auto liability framework—the driver is responsible for negligence, and the vehicle owner’s insurance may be called into play. However, courts are beginning to treat the platform as a third‑party intermediary, imposing duties that resemble those of a transportation network company.
Liability: When the Driver Isn’t the Owner
Imagine a scenario where a renter rear‑ends a parked car during a rainy evening. Who pays?
- The renter’s personal auto policy – if they have one that covers non‑owned vehicles. Many renters don’t, leaving a coverage gap.
- The owner’s policy – may extend coverage under “permitted driver” clauses, but insurers often exclude “commercial use” without endorsement.
- The platform’s liability – increasingly, platforms offer a “host protection insurance” that fills the gap, but its limits and exclusions vary dramatically.
Recent case law suggests that when a platform advertises “comprehensive coverage,” courts may view it as an implied guarantee, subjecting the platform to negligence claims if the coverage is inadequate. This is a trend we’ve seen across gig‑based services, where the intermediary’s promises become contractual obligations.
Insurance Innovations and Their Pitfalls
To address the coverage void, many P2P platforms have rolled out on‑demand insurance products that activate the moment a reservation is confirmed. These policies typically include:
- Liability limits (often $1 million combined single‑limit).
- Collision and comprehensive coverage with a deductible.
- Supplemental medical payments for occupants.
While attractive, the fine print often reveals exclusions for:
- Use in certain jurisdictions (e.g., states with stricter commercial vehicle regulations).
- Driving under the influence or reckless behavior.
- Vehicle modifications that affect safety systems.
Owners who rely solely on platform‑provided coverage without reviewing their personal policies may find themselves underinsured when a claim exceeds the platform’s limits. This is why it’s critical to conduct a “coverage overlay analysis” before listing a vehicle.
Consumer Protection: The Renter’s Perspective
Renter expectations are shaped by the seamless experience that platforms promise: instant booking, transparent pricing, and “all‑inclusive” insurance. When an accident occurs, renters often feel blindsided by:
- Unexpected deductibles.
- Delayed claim processing.
- Ambiguous responsibility for vehicle damage beyond the deductible.
State consumer protection statutes—such as the Unfair and Deceptive Acts and Practices (UDAP) laws—can be invoked if a platform’s marketing creates a material misrepresentation about coverage. In a few recent lawsuits, courts have allowed renters to claim damages for “misleading coverage statements,” even when the platform’s policy language technically covered the scenario.
Regulatory Landscape: A Patchwork of State Rules
Unlike traditional car rentals, which are governed by well‑established federal and state regulations, P2P platforms face a mosaic of state statutes:
- California – Requires platforms to hold a “motor vehicle rental license” and maintain a minimum liability insurance level.
- New York – Mandates that platforms disclose the exact insurance limits and provide a copy of the policy to renters.
- Texas – Allows “owner‑provided coverage” if the owner’s policy explicitly names the renter as an additional driver.
Because the rules differ so dramatically, platforms often adopt the most restrictive standards across all states to simplify compliance, which can increase operational costs and affect pricing for users.
Data Privacy Meets Liability
Every P2P transaction generates a trove of data: GPS traces, driver behavior metrics, and even facial recognition images for verification. While data privacy is a separate legal domain, its mishandling can amplify liability:
- If a platform’s data breach reveals a renter’s location at the time of an accident, the owner could be sued for invasion of privacy.
- Improper data retention may violate state privacy statutes, exposing the platform to additional fines.
These concerns echo the challenges outlined in the legal frontier of subscription‑based vehicle features and OTA updates, where data security and consumer rights intersect.
Contract Drafting: Best Practices for Owners and Platforms
To mitigate risk, both parties should prioritize clear, enforceable contracts. Here are essential clauses:
- Indemnification – The renter should agree to indemnify the owner and platform for claims arising from the renter’s negligent conduct.
- Insurance Confirmation – Require renters to upload proof of personal coverage or accept the platform’s insurance terms explicitly.
- Vehicle Condition Checklist – A pre‑rental inspection form signed by both parties reduces disputes over pre‑existing damage.
- Data Usage Consent – Clearly explain how telematics data will be used, stored, and shared.
- Termination Rights – Allow the platform to suspend or cancel a reservation if the renter violates policy or law.
Emerging Trends: From Micro‑Mobility to Fleet‑Level Sharing
Beyond individual owners, corporations are deploying fleets of shared vehicles for employee use or public‑facing services. This raises additional layers of compliance:
- Employer Liability – If an employee uses a shared vehicle for business, the employer may be vicariously liable under workers’ compensation statutes.
- Commercial Registration – Some jurisdictions require fleet vehicles to be registered as commercial, triggering higher insurance premiums.
- Environmental Reporting – Companies may need to disclose fleet emissions as part of ESG (Environmental, Social, Governance) reporting.
These developments hint at a future where P2P platforms must integrate not only consumer‑focused policies but also corporate compliance frameworks.
Practical Checklist for Vehicle Owners
Before you list your car, run through this quick audit:
- Review your personal auto policy for “non‑owner” coverage and discuss any necessary endorsements.
- Read the platform’s insurance terms line‑by‑line; note deductible amounts and exclusions.
- Document your vehicle’s condition with dated photos and a signed checklist.
- Ensure your registration and inspection are up to date in every state where you’ll rent.
- Consider a separate umbrella policy to protect against claims that exceed platform limits.
Advice for Renters: Protect Yourself Before You Hit the Road
Even with platform insurance, it’s wise to:
- Carry your own personal auto insurance card; many policies extend to “temporary use” of other vehicles.
- Ask for a copy of the platform’s insurance certificate before the rental begins.
- Inspect the vehicle for damage and report any issues immediately to avoid being held liable.
- Familiarize yourself with the state’s minimum liability requirements; you may need to purchase supplemental coverage.
Looking Ahead: Legislative Initiatives on the Horizon
Lawmakers are beginning to recognize the unique nature of P2P car sharing. Bills under consideration in several states aim to:
- Standardize minimum insurance limits across all platforms.
- Require platforms to maintain a “risk pool” fund that can cover claims exceeding policy limits.
- Mandate real‑time disclosure of coverage details during the booking process.
- Establish a clear “primary vs. secondary” insurance hierarchy between renter, owner, and platform.
These proposals, if enacted, could bring much‑needed uniformity but also increase compliance costs for platforms and owners alike.
Conclusion: Navigate the Legal Terrain With Eyes Wide Open
Peer‑to‑peer car sharing is a dynamic, democratizing force in transportation, but it sits at the intersection of contract law, insurance regulation, consumer protection, and data privacy. By understanding the nuanced liability landscape, aligning insurance coverage, and drafting robust agreements, owners, renters, and platforms can enjoy the benefits while minimizing legal exposure. As the industry matures, staying ahead of emerging statutes and court decisions will be essential—because in the world of shared mobility, the only constant is change.
I am Madden Persons, a content writer and digital influencer dedicated to crafting impactful stories and building authentic online connections. With a strategic approach to content creation, I develop engaging articles, digital campaigns, and social media narratives that help brands elevate their online presence and connect meaningfully with their target audiences.
Passionate about modern digital trends and audience engagement, I specialize in translating complex ideas into compelling content that sparks conversation, drives results, and strengthens brand identity.
Related Posts
When Autonomous Vehicles Crash: Untangling Fault, Liability, and the Future of Automotive Law
A deep dive into the legal complexities of autonomous vehicle crashes, offering clear guidance on fa... Read More

Software Updates, Ownership, and Liability: The New Frontier in Automotive Law
As vehicles become software‑defined platforms, over‑the‑air updates blur the line between prod... Read More
The Hidden Legal Maze of Car Subscription Services
Vehicle subscriptions promise flexibility, but they hide legal complexities. Learn how to navigate c... Read More
Top Posts
How Influencer Culture is Redefining Intellectual Property Rights
In the era of viral videos and TikTok trends, creators face unique IP challenges; this guide reveals practical steps to protect their work and monetize collabor...Read More
Telehealth Across State Lines: Navigating Consent and Liability in Modern Medical Law
A deep dive into the legal challenges of telemedicine across state lines, offering practical guidance on consent, licensing, liability, and insurance for modern...Read More
Navigating Modern Marriage Law in a Digital World
Discover the latest digital trends influencing marriage law, including blockchain licenses, AI tools, and virtual courts, plus a handy checklist for tech‑savv...Read More
Navigating Copyright for AI‑Generated Creations
A deep dive into the legal maze surrounding AI‑created works, offering actionable advice for protecting your innovations in a rapidly evolving IP landscape....Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!